
Fast business funding for liquor store owners
Liquor Store Financing, approved the same day.
From $5,000 to $1.5 million for inventory, coolers, remodels, and working capital. Fixed payments, no daily debits, and one specialist who understands how a liquor store actually runs.
- Same-day callback, and same-day approval once you send 3 bank statements
- Funding in 3–7 business days, not the weeks a bank takes
- Fixed payments with terms up to 36 months, not a cash advance
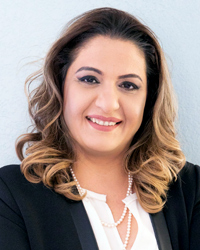
Marie Lokmanyan, your funding specialist. 20 years in commercial banking.
Prefer to talk? (310) 402-1600
What do you need funding for?
Funding for every part of running a liquor store
Pick what you're working on. We'll show you how it's typically financed, what it costs, and how fast you can get it.
Inventory & holiday stock-ups
Load up for Q4, deal buys, and allocations without draining your operating account.
Learn more →Working capital
Cover payroll, taxes, COD distributor bills, and slow months with fixed payments.
Learn more →Coolers & equipment
Walk-ins, beer caves, compressors, POS, and security, often funded in 3–7 business days.
Learn more →Remodel or expand
Add cooler doors, a wine room, new signage, or open a second location.
Learn more →Get off daily debits
Replace expensive merchant cash advances with one fixed payment.
Learn more →Line of credit
Draw when you need it, repay, and draw again for the next season.
Learn more →Buy a liquor store
How acquisitions are financed, and what lenders need from the seller.
Learn more →SBA loans & bridge funding
Long-term SBA options, plus bridge funding while your SBA loan is in process.
Learn more →Why liquor store owners call us
Generic lenders don't understand liquor stores. We work with nothing else.
- COD distributor terms. Tied-house rules mean your suppliers can't float you, so you fund your own inventory. We size funding around that reality.
- Q4 is make-or-break. We plan for the holiday inventory build-up, not after it.
- Cash-heavy sales. We look at your bank deposits and real sales, not just a credit score.
- Thin margins. Fixed payments you can plan around beat daily debits that eat your register.
Same $100,000. Very different month.
1.35 factor, repaid over ~8 months≈ $16,875/mo
24-month term, assumed 18% APR≈ $4,992/mo
Illustrative math only, not an offer. Your rate and terms depend on your store's numbers. Run your own numbers →
How it works
Three steps to your numbers
- 1
Tell us about your store
Two minutes: what you need, your monthly sales, and how to reach you. No effect on your credit. We'll get back to you the same business day.
- 2
Talk to your specialist
Your specialist reviews your request, asks for your last 3 bank statements, and answers your questions.
- 3
Get approved and funded
Send your 3 most recent bank statements and get approved the same day. Sign, and funds are typically in your account within 3–7 business days.
Meet your funding specialist
A real person who's been doing this for 20 years
When you reach out, you won't be passed around a call center. Your request goes to Marie Lokmanyan, who has spent two decades in commercial banking and business lending, including more than ten years as a private banker at Wells Fargo.
“I am a firm believer in supporting local businesses, which is why I am passionate about helping local businesses grow.”
- 20 years in commercial banking and business lending
- Former Private Banker at Wells Fargo for more than 10 years
- Business funding consultant to small businesses since 2016
- B.S. in Business Administration, New York University
Do I qualify?
What you need to get pre-approved
- You own an operating liquor, wine, or beer store (open at least 30 days under your ownership)
- Monthly sales of about $17,000 or more (cash + card combined)
- Personal credit score of about 575 or higher
- Your 3 most recent business bank statements
Don't meet every point? Reach out anyway. We'll tell you honestly what's possible, including SBA and other routes for new stores and acquisitions.
Check if my store qualifies →